
By Hernan Lopez.
Companies mentioned: Amazon, AMC Networks, Disney, Fox, Google, NBCU, Netflix, Skydance, YouTube
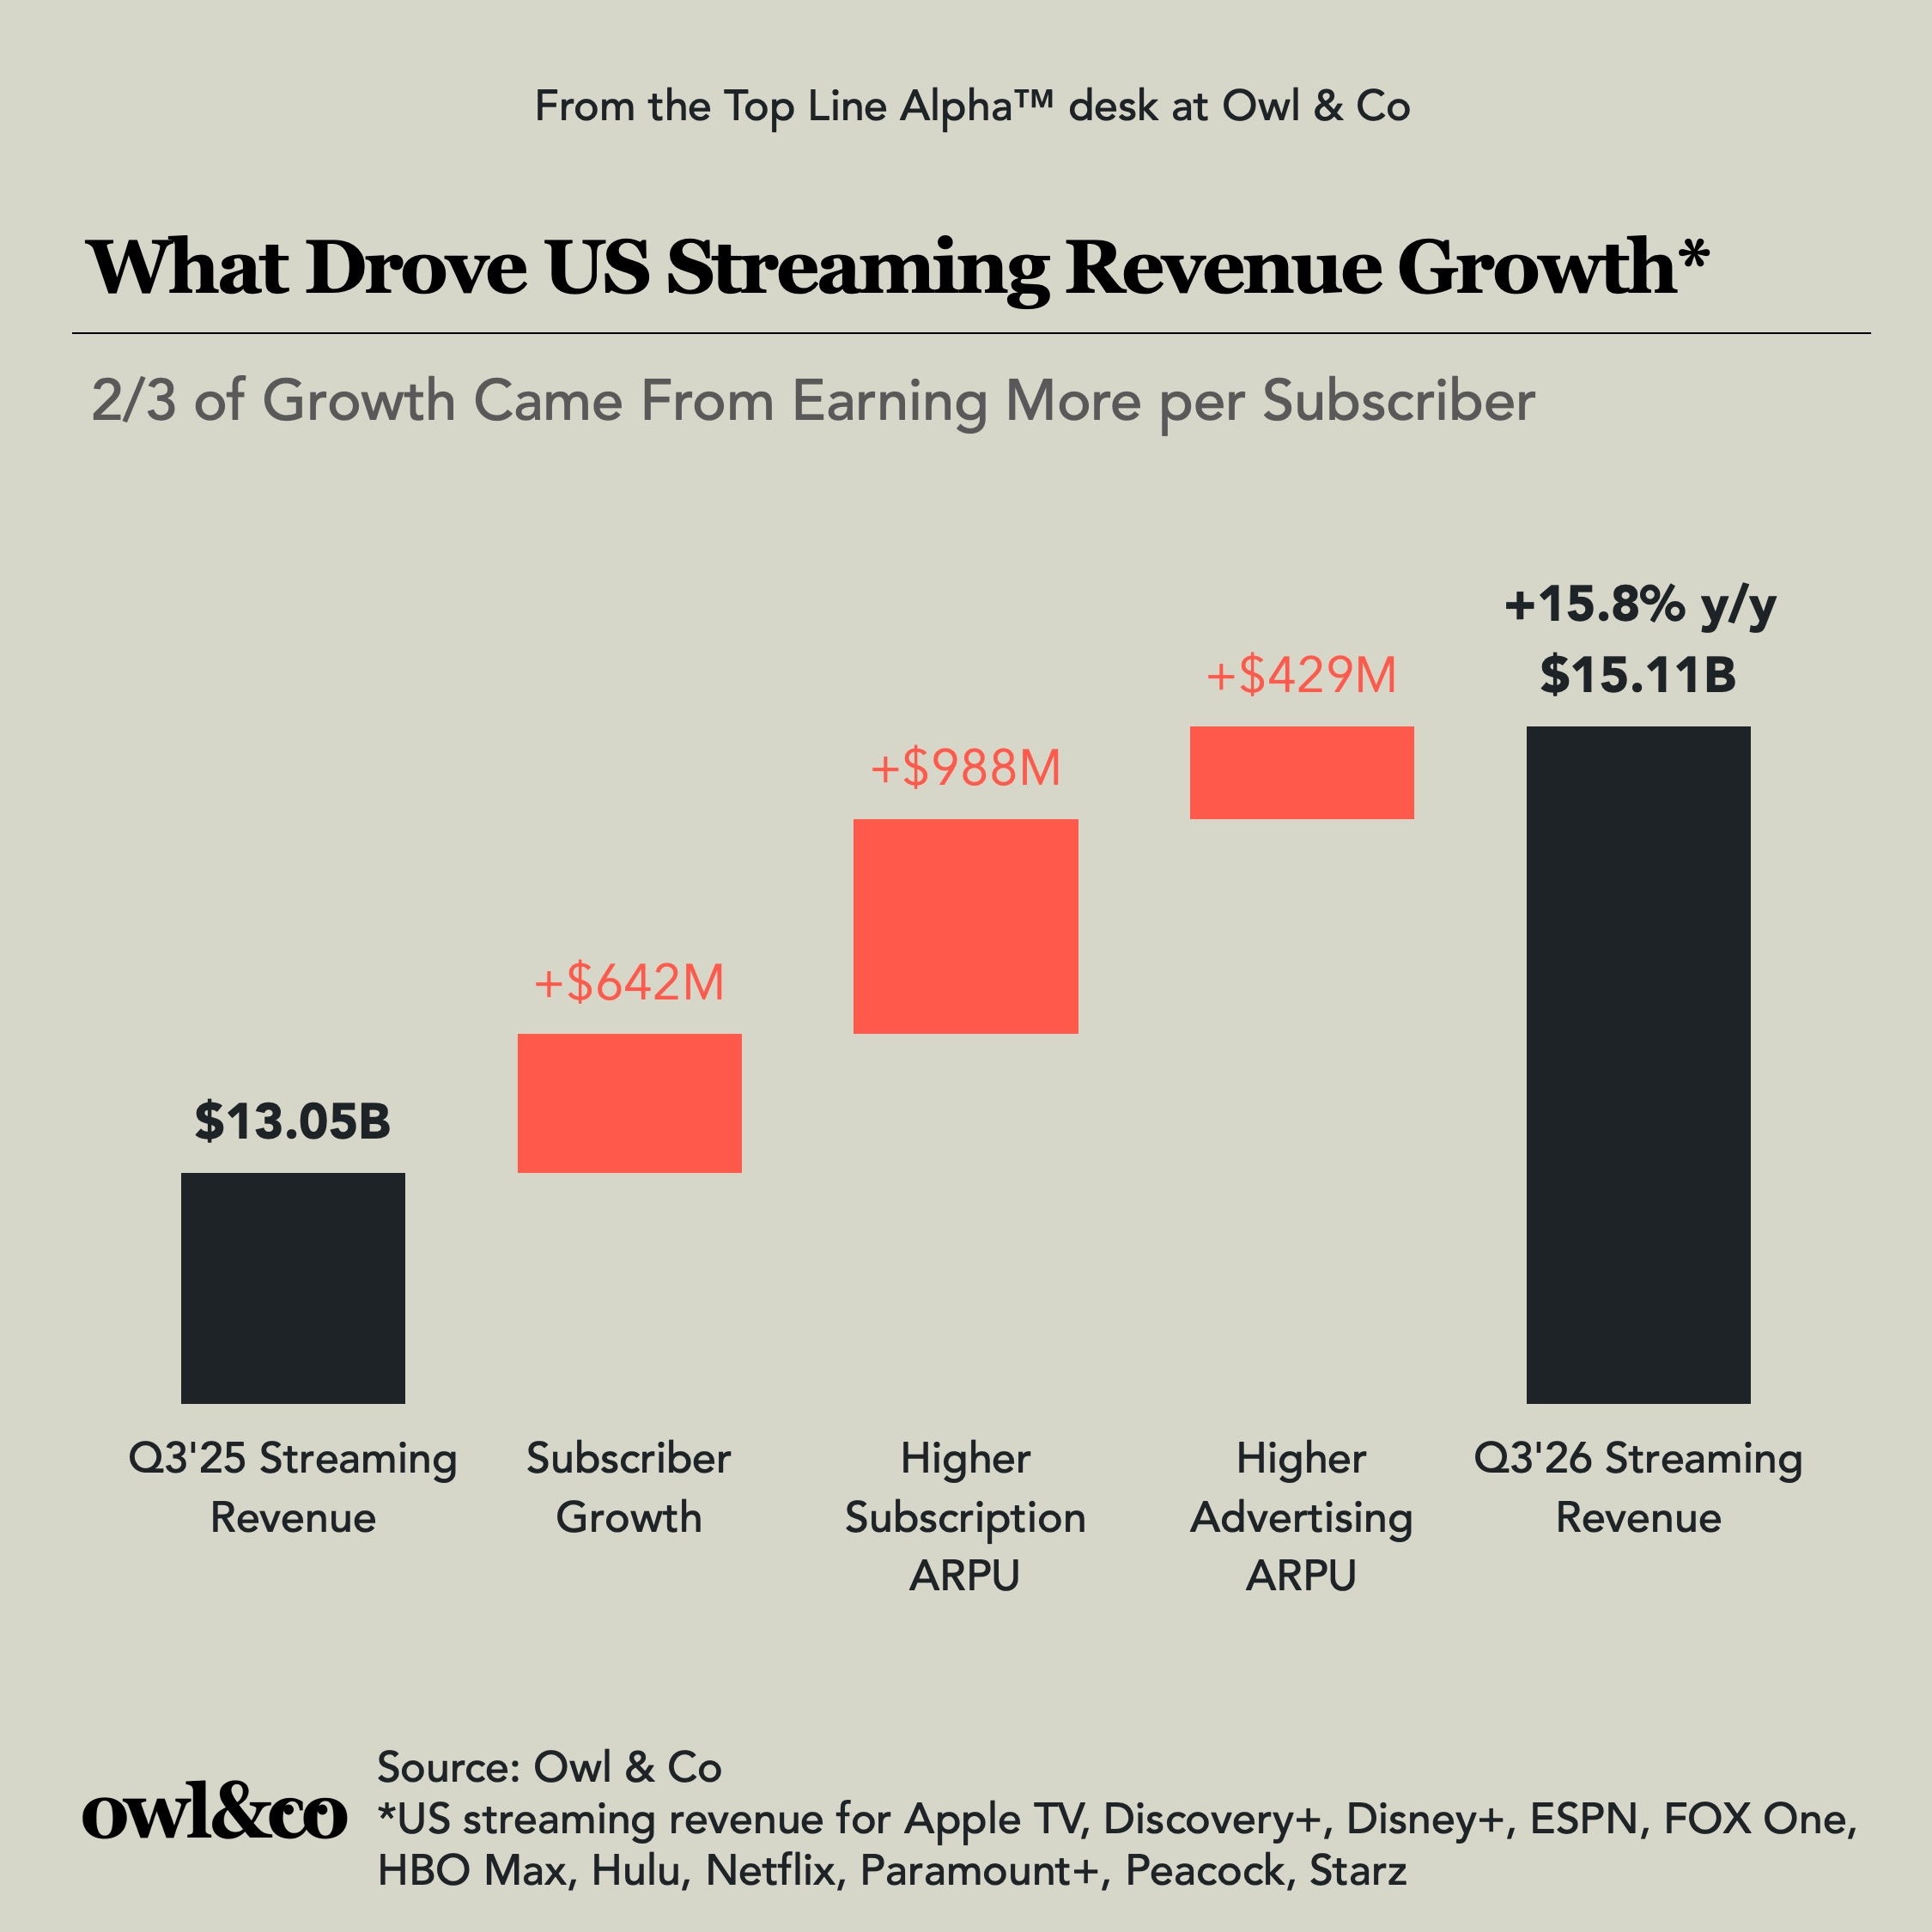
Questions answered: If US Premium SVOD services lost 1.7M subs in Q3, how much revenue did they gain YoY, and where did the growth come from? Which Premium SVOD service has the highest Ad ARPU? When did US Pay TV subscribers and cable network profits peak, and does that say something about streaming? Is Owl & Co hiring?
Special note: This is a public version of the Streamonomics® newsletter. I send an exclusive version to clients one day in advance, which includes more in-depth analysis, access to Owl & Co proprietary research, and opinions not included in the public version. If you work for an Owl & Co client (or would like to become one), just reply.
The Streaming Seven delivered in Q3. So why is there so much anxiety? Theory one: Less disclosure cuts both ways. Streamers keep some of their best metrics private, leaving investors to guess whether they’re strong or weak and what they signal about the future. When Amazon says Prime Video has a “revenue run rate in the tens of billions and profitable in its own right,” how are investors to know that it’s getting closer to Netflix-scale revenue each quarter? When YouTube gets dinged for decelerating to single-digit ad revenue growth, how would anyone know that subscriptions are growing fast enough to put YouTube on track for $10B in operating income this year?